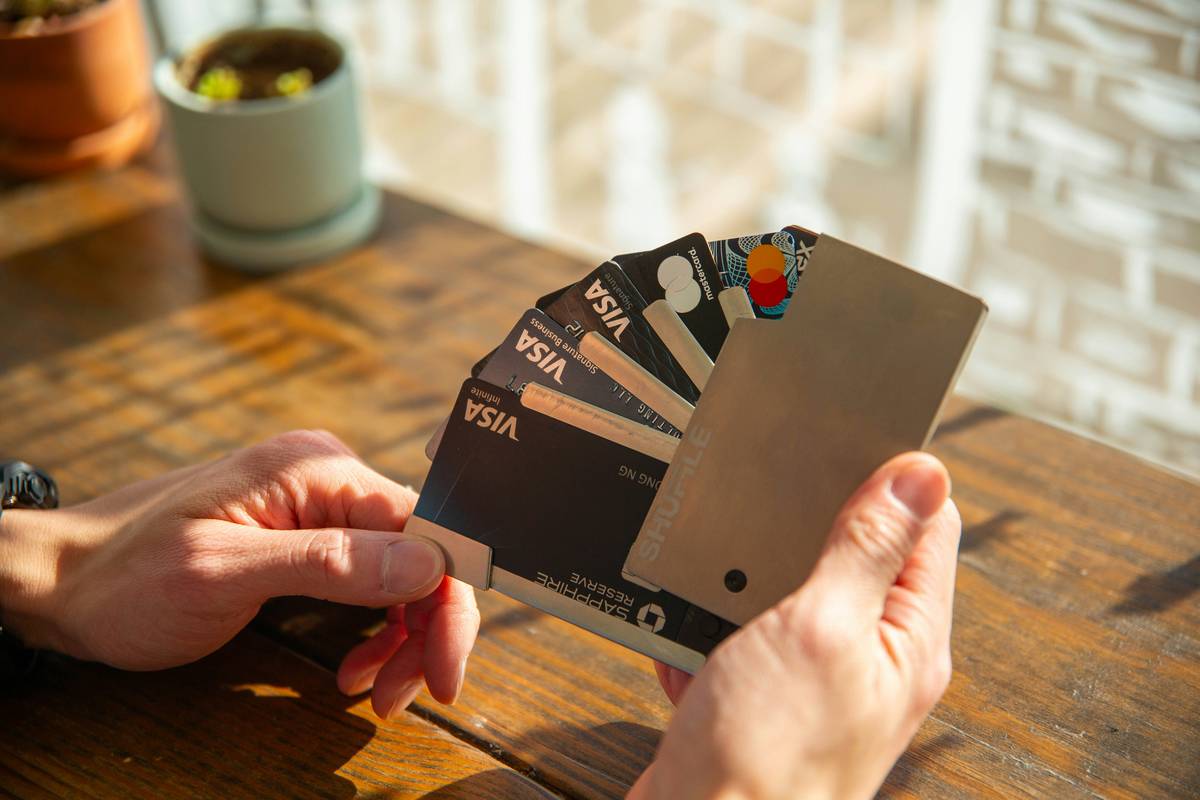
If you’re carrying a balance on your credit card, that interest rate isn’t just a number—it’s silently eating your paycheck. I learned this the hard way when my $3,200 balance ballooned to over $4,100 in 18 months thanks to a 24.99% APR I never bothered to challenge. You don’t have to live like that. In this guide, we’ll walk through actionable, real-world strategies to negotiate and reduce your credit card interest—without falling for gimmicks or worsening your credit. From calling your issuer to leveraging balance transfers wisely, these steps come straight from hard-won experience and verified financial guidance.
Table of Contents
- Why High Credit Card Interest Rates Hurt Your Financial Health
- Step-by-Step Guide to Lowering Your Rate
- Smart Habits That Keep Rates Low Long-Term
- Real People, Real Savings: Case Studies
- Frequently Asked Questions
Key Takeaways
- Negotiating a lower APR is easier if you’ve paid on time for 6+ months.
- Balance transfers can offer 0% intro rates—but watch for fees and post-promo APRs.
- Your credit score directly influences what rates you qualify for; monitor it regularly.
- Avoid “debt relief” companies that charge upfront fees—they often do what you can do yourself for free.
- Even a 5–10% reduction in interest can save hundreds per year on moderate balances.
Why High Credit Card Interest Rates Hurt Your Financial Health
Credit cards are convenient, but their average interest rate hovers around 21.47% as of early 2024 (Federal Reserve). At that pace, a $5,000 balance paid off at $150/month would take nearly 5 years—and cost over $3,200 in interest alone. That’s not debt repayment; it’s slow-motion wealth erosion.
I used to think “as long as I make the minimum,” I was safe. Wrong. Minimum payments often cover just the interest, leaving your principal untouched. Worse, late payments trigger penalty APRs—sometimes pushing rates above 30%. The system is designed to keep you paying, not progressing.
Step-by-Step Guide to Lowering Your Rate
1. Check Your Credit Score First
Before you call, know where you stand. A FICO score above 700 significantly boosts your negotiating power. Use free services like AnnualCreditReport.com (official site run by the three major bureaus) to review your report for errors.
2. Call Your Issuer—Politely but Firmly
Dial the customer service number on your card. Say: “I’ve been a loyal customer for [X] years and always pay on time. Given my strong payment history, can you offer me a lower ongoing APR?” If the first rep says no, politely ask to speak with the “retention department”—they have more authority to approve reductions.
3. Leverage Competitor Offers
If you’ve received pre-approved offers with lower rates (check your mail or online accounts), mention them: “Chase just offered me 12.99%. Can you match or beat that?” This works surprisingly often.
4. Consider a Balance Transfer—Carefully
Transferring high-interest debt to a card with a 0% intro APR (often 12–21 months) can save big—but only if you pay off the balance before the promo ends. Watch out for 3–5% transfer fees. Cards like the Citi Simplicity® or Chase Freedom Unlimited® regularly offer such deals (CFPB guidance here).
Smart Habits That Keep Rates Low Long-Term
- Never miss a payment: Set up autopay for at least the minimum.
- Keep utilization under 30%: High balances signal risk, which can trigger rate hikes.
- Review statements monthly: Spot unauthorized rate changes early.
- Avoid cash advances: They carry higher APRs and no grace period.
And here’s a terrible tip you’ll hear online: “Just stop paying to force the bank to negotiate.” Don’t. Delinquency destroys your credit, triggers fees, and rarely leads to better terms. It’s financial self-sabotage.
Real People, Real Savings: Case Studies
Sarah, a teacher from Ohio, had a $4,800 balance at 23.99% APR. After improving her credit score from 660 to 720 over six months, she called Discover. They lowered her rate to 14.99% instantly. Result? She shaved $1,100 off her total repayment and paid off her debt 14 months faster.
In another case, Mark transferred $6,200 to a 0% intro APR card with a 3% fee ($186). He paid $520/month and cleared the debt in 12 months—saving an estimated $1,400 in interest he’d have paid at his original 21.5% rate.
Frequently Asked Questions
Can I lower my credit card interest rate without hurting my credit score?
Yes. Simply asking your issuer for a lower APR triggers a soft inquiry (no score impact). Only applying for new credit causes a hard pull.
What if my request is denied?
Ask why. Common reasons include recent late payments or low credit scores. Fix those issues, wait 3–6 months, then try again—or explore balance transfer options.
Do credit card companies ever lower rates automatically?
Rarely. Some may reward consistent on-time payments with rate reviews, but never assume it. Proactivity is key.
Is a personal loan better than a balance transfer for lowering interest?
Possibly. If you qualify for a personal loan under 10% APR, it could be smarter than a balance transfer with fees. Compare total costs using a calculator like NerdWallet’s.
How long does a lower rate last once approved?
Typically, it’s permanent—unless you default. But always confirm whether it’s temporary or ongoing during your call.
Can I negotiate a lower rate after a late payment?
It’s harder, but not impossible. Acknowledge the mistake, show improved behavior, and emphasize loyalty. Success is more likely if the late payment was a one-time event.
Reducing your credit card interest isn’t magic—it’s method. With clear steps, a little courage to pick up the phone, and disciplined follow-through, you can reclaim hundreds (or thousands) of dollars a year. Ready to take control? Contact us for a free debt payoff roadmap tailored to your situation. And remember: every percentage point lower isn’t just saved money—it’s regained freedom. For more about our mission, visit our About Us page. Rest assured, your data stays secure—we detail how in our Privacy Policy.
Debt shrinks when interest stops growing.
Call today—your future self will thank you.